Research by MICKE
Author: micke
- 2.00 +4.82% (31/12/2027)
- MONITOR (BUY)
Intrum is a potential turnaround case with vision to have solid finances FY28. Intrum has been through Chapter 11 in 2025 and has raised SEK 7.5 billion July 2026. The company had a lot of debt 46 billion before the capital raise. The Price/Book value looks good at first glance, but there is about 33 billion of Intangible assets on the balance sheet, which I guess isn't worth much in reality. There is about 20 billion of assets related to investments in debt that is part of the company's core business to work with. There are several analysts and all of them have a positive outlook. I was optimistic after Q2 but feel that the future is more unclear after Q3.
Valuation (1)
Their business is profitable and EBIT is good. But they need a lot of capital, thus the EPS when interest etc is deducted is more relevant for me.
29/08/2026 by MICKE|1
Business (1)
As I understand it from Intrum's presentations they are the largest EU company in their business, which should be good. I don't know this business that well but it is normally good to be a leader.
29/08/2026 by MICKE|1
Financial (1)
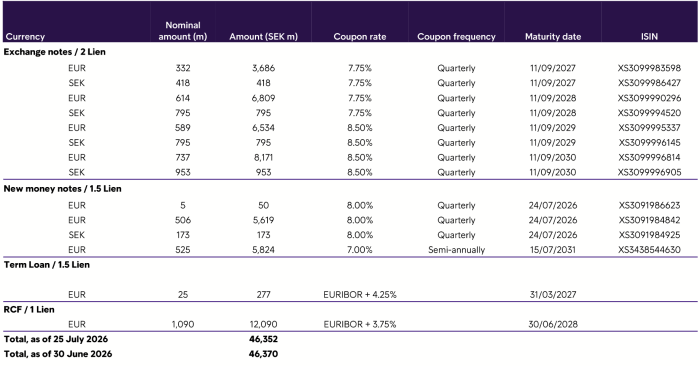
A lot of debt around 40 billion after the capotal raise of 7.5 billion. This needs to come down if the turn around shall be successful.
 29/08/2026 by MICKE|1